ConocoPhillips NYSE: COP reported third-quarter adjusted earnings of $3.27 per share and $7.2 billion in cash from operations, while raising its quarterly dividend by 11% and outlining plans for lower capital spending in 2027.
ConocoPhillips' Q2 2026 results show a dramatic revenue and EPS surge (29.4% YoY revenue growth, 107.1% EPS growth), but the zero COGS and SG&A volatility suggest data anomalies that warrant caution.
Price trend, volume and key moving averages
Start with the evidence for owning the stock and the risks that can break the thesis.
Revenue surged 29.4% YoY to $18.1B in Q2 2026 with EPS up 107.1%, but gross margin of 100% is a data artifact (COGS reported as zero), and margins have ranged from 19.6% to 30.6% over the past year, indicating volatile, commodity-driven profitability.
Many analysts have issued 'Buy' or 'Overweight' ratings for ConocoPhillips (COP), with median price targets suggesting potential upside from current levels, ranging from $131.36 to $140.00, and the highest projections reaching up to $183.00.
ConocoPhillips maintains a strong market capitalization and a relatively low debt-to-equity ratio, indicating financial stability and a lower risk profile.
The company's expanding LNG portfolio and progress on large-scale liquefaction projects like those in Qatar, Port Arthur, and Willow are expected to drive substantial free cash flow and revenue expansion through 2029.
Ongoing geopolitical tensions, particularly in the Middle East, could negatively impact oil prices and demand, posing risks to ConocoPhillips' profitability, especially given its unhedged position.
The growing trend towards renewable energy may lead to a structural shift away from fossil fuels, potentially affecting long-term demand for oil producers like ConocoPhillips.
ConocoPhillips has seen its net profit margins slip from 16.3% to 13.2% over the last year, with recent quarters not showing a clear improvement.
Trailing total returns as of 11/7/2026, which may include dividends or other distributions. Benchmark is S&P 500 (^GSPC).
Check whether operating performance supports the current valuation.
Recent results and news deserve attention only when they alter the forward view.
| Quarter | EPS (Act vs Est) | Revenue (Act vs Est) |
|---|---|---|
Q4 2026Latest Nov 5, 2026 | $3.27+7.2% vs $3.05 | $20.1B+7.9% vs $18.6B |
Q3 2026 Aug 6, 2026 | $3.24+11.7% vs $2.90 | $19.5B+3.9% vs $18.8B |
Q2 2026 Apr 30, 2026 | $1.89+9.9% vs $1.72 | $16.1B+2.8% vs $15.6B |
Q1 2026 Feb 5, 2026 | $1.02-4.7% vs $1.07 | $14.2B+1.7% vs $13.9B |
ConocoPhillips NYSE: COP reported third-quarter adjusted earnings of $3.27 per share and $7.2 billion in cash from operations, while raising its quarterly dividend by 11% and outlining plans for lower capital spending in 2027.
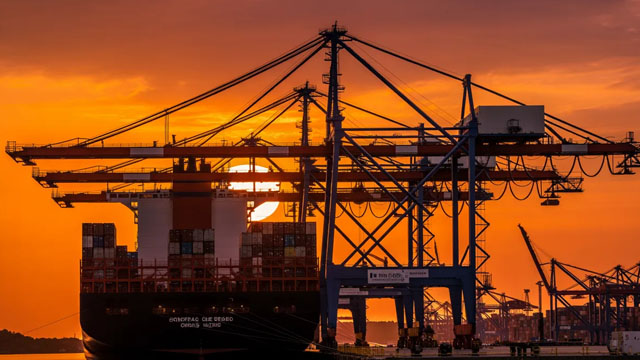
Two oil producers just posted strong quarters, but only one turned its cash flow into a payout that can survive a price slump. For income investors, the gap between a bigger yield and a safer check may surprise you.

ConocoPhillips targets $7B in free cash flow improvement by 2029, with lower capital spending, growing production and higher shareholder returns driving its outlook.

ConocoPhillips delivered strong third-quarter results, generating gushing cash flows to support healthy cash returns to shareholders. The oil producer raised its dividend by 11% and reaffirmed its plan to deliver $7 billion in additional free cash flow by 2029.

Benchmark COP against direct peers instead of judging its metrics in isolation.
Key metrics vs top competitors for ConocoPhillips (COP)
| Company | Price | Market Cap | P/E Ratio | Rev Growth (1Y) | Net Margin | ROE | Div Yield |
|---|---|---|---|---|---|---|---|
| $136.27 | $166.02B | 21.46 | 7.51% | 13.6% | 12.36% | 2.34% | |
| $147.13 | $78.37B | 16.15 | -3.47% | 25.71% | 22.38% | 2.72% | |
| $42.21 | $29.56B | 10.05 | 7.83% | 16.67% | 14.9% | 2.33% | |
| $44.63 | $15.78B | 11.19 | -8.39% | 18.99% | 22.97% | 2.25% | |
| $178.96 | $50.34B | 31.23 | 36.31% | 11.67% | 4.97% | 2.23% | |
| $56.38 | $56.08B | 35.02 | -20.32% | 28.79% | 25.7% | 2.83% |
ConocoPhillips (COP) vs competitors — business, growth, and fundamentals comparison against the closest industry rivals.
Verify the primary filings, follow material updates, and answer the remaining questions.
ConocoPhillips (COP) SEC filings — annual & quarterly reports (10-K, 10-Q)
Aug 11, 2026·SEC
Aug 6, 2026·SEC
Jun 23, 2026·SEC
Get notified when COP posts new earnings or crosses analyst targets
Free. No account needed. Unsubscribe any time.
ConocoPhillips (COP) stock FAQ — growth, dividends, profitability & financials explained
ConocoPhillips (COP) reported $62.42B in revenue over the trailing twelve months. Revenue was $58.71B in fiscal year 2025. That is 271% more than the $15.81B of fiscal year 1996.
ConocoPhillips (COP) grew revenue by 7.5% in fiscal year 2025, compared with the prior fiscal year.
Yes. ConocoPhillips (COP) earned $9.28B in net income over the trailing twelve months (a 14.9% net margin).
Yes. ConocoPhillips (COP) pays a dividend that yields 2.34% at the current price, a moderate yield.
ConocoPhillips (COP) had a return on equity (ROE) of 12.4% in fiscal year 2025. That is in line with the market's typical 10-15%.
ConocoPhillips (COP) generated $19.59B in free cash flow over the trailing twelve months.