PRNewsWire·22h ago
AI Revenue Questions Pull Semiconductor Stocks Off October Highs/PRNewswire/ -- Stock Preachers News Commentary - Semiconductor equities began October on firm footing, with the iShares Semiconductor ETF advancing for five

Micron's revenue has expanded roughly eight-fold from $6.8 billion in 2024Q3 to $54.2 billion in 2026Q4 as AI-driven HBM and DDR5 demand drove gross margin to an unprecedented 86.8% and operating margin to 80.7%, while the balance sheet has been fundamentally ...
Price trend, volume and key moving averages
Start with the evidence for owning the stock and the risks that can break the thesis.
Revenue growth has decelerated to 3.8% year-over-year in 2026Q4 despite gross margin surging to 86.8% and operating margin to 80.7%, an outlier spread versus Seagate's 33.6% that may indicate pricing gains are approaching cyclical extremes rather than reflecting a structurally superior model.
Micron's HBM capacity for 2026 is reportedly sold out, driven by insatiable demand for AI computing power.
Q2 FY2026 revenue surged by 196% year-over-year to $23.86 billion, with non-GAAP EPS increasing by 682%.
Micron has secured a five-year Strategic Customer Agreement, ensuring multiyear demand visibility.
The semiconductor memory market is cyclical, and a downturn could lead to oversupply and price erosion.
Micron faces significant competition in the memory chip market, which could impact pricing and market share.
Success relies on the ramp-up of HBM4 production; any delays could negatively affect stock performance.
Trailing total returns as of 10/11/2026, which may include dividends or other distributions. Benchmark is S&P 500 (^GSPC).
Check whether operating performance supports the current valuation.
Recent results and news deserve attention only when they alter the forward view.
| Quarter | EPS (Act vs Est) | Revenue (Act vs Est) |
|---|---|---|
Q4 2026Latest Sep 30, 2026 | $33.42+5.2% vs $31.77 | $54.2B+5.6% vs $51.3B |
Q3 2026 Jun 24, 2026 | $25.11+19.7% vs $20.98 | $41.5B+15.4% vs $35.9B |
Q2 2026 Mar 18, 2026 | $12.20+32.8% vs $9.19 | $23.9B+19.5% vs $20.0B |
Q4 2025 Dec 17, 2025 | $4.78+20.7% vs $3.96 | $13.6B+5.7% vs $12.9B |
/PRNewswire/ -- Stock Preachers News Commentary - Semiconductor equities began October on firm footing, with the iShares Semiconductor ETF advancing for five
The best time to buy is at the time of maximum AI pessimism, given the serious disconnect between Micron's robust fundamentals and discounted stock valuations/prices. The 26 SCAs lock in RPOs worth $150B through 2031 and cash commitments of $32B, providing multi-year revenue visibility while mitigating the sector's cyclical risks. Memory/storage oversupply risks have been overstated, given the ongoing power grid interconnection delays and the next decade's physical AI (robots/autonomous) tailwinds.
Retail investors talked up five hot stocks during the week (Oct. 5 to Oct. 9) on X and Reddit's r/WallStreetBets, driven by retail hype, earnings, AI infrastructure momentum, and corporate news flow.
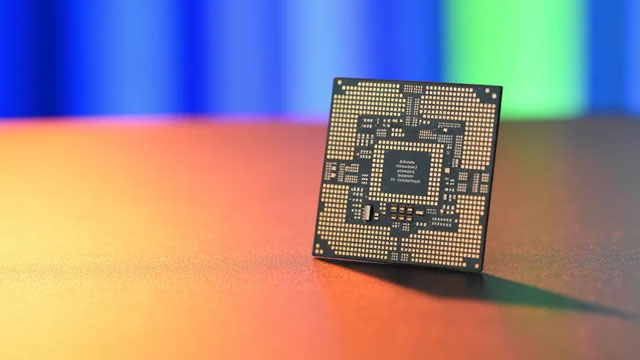
Micron Technology (NASDAQ: MU) could plunge to $400 in early June 2027 if its current rally repeats a price pattern from the Dot-com bubble.
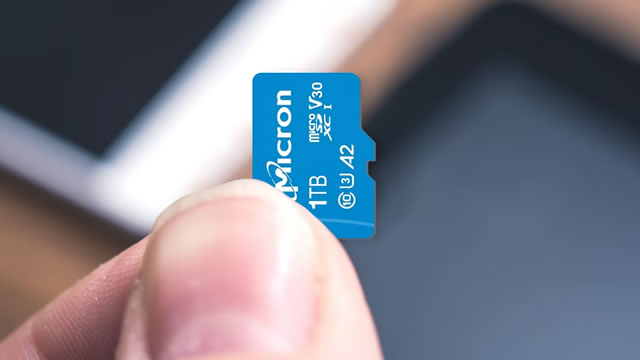
Benchmark MU against direct peers instead of judging its metrics in isolation.
Key metrics vs top competitors for Micron Technology, Inc. (MU)
| Company | Price | Market Cap | P/E Ratio | Rev Growth (1Y) | Net Margin | ROE | Div Yield |
|---|---|---|---|---|---|---|---|
| $1029.00 | $1.16T | 135.57 | 48.85% | 22.84% | 17.2% | 0.05% | |
| $104.70 | $528.11B | -1777.59 | -0.47% | -19.79% | -9.58% | — | |
| $397.28 | $136.94B | 16.02 | 35.7% | 72.95% | 118.65% | — | |
| $783.00 | $175.57B | 56.33 | 34.06% | 26.11% | 348.17% | — | |
| $95.65 | $2.36B | 20.48 | -3.65% | 6.6% | 9.1% | — | |
| $30.54 | $15.82B | -0.89 | -6.14% | -159.3% | -282.74% | — |
Micron Technology, Inc. (MU) vs competitors — business, growth, and fundamentals comparison against the closest industry rivals.
Verify the primary filings, follow material updates, and answer the remaining questions.
Micron Technology, Inc. (MU) SEC filings — annual & quarterly reports (10-K, 10-Q)
Sep 30, 2026·SEC
Jun 24, 2026·SEC
Jun 9, 2026·SEC
Get notified when MU posts new earnings or crosses analyst targets
Free. No account needed. Unsubscribe any time.
Micron Technology, Inc. (MU) stock FAQ — growth, dividends, profitability & financials explained
Micron Technology, Inc. (MU) reported $133.19B in revenue for fiscal year 2025. This represents a 3545% increase from $3.65B in 1996.
Micron Technology, Inc. (MU) grew revenue by 48.9% over the past year. This is strong growth.
Yes, Micron Technology, Inc. (MU) is profitable, generating $84.97B in net income for fiscal year 2025 (22.8% net margin).
Micron Technology, Inc. (MU) does not currently pay a meaningful dividend. The company may be reinvesting profits for growth.
Micron Technology, Inc. (MU) has a return on equity (ROE) of 17.2%. This is reasonable for most industries.
Micron Technology, Inc. (MU) generated $52.91B in free cash flow for fiscal year 2025. Positive FCF indicates the company can fund dividends, buybacks, or reinvestment.