ZIM's Q3 earnings are likely to have benefited from stronger freight rates, Transpacific demand and capacity constraints, though elevated bunker costs remain a concern.
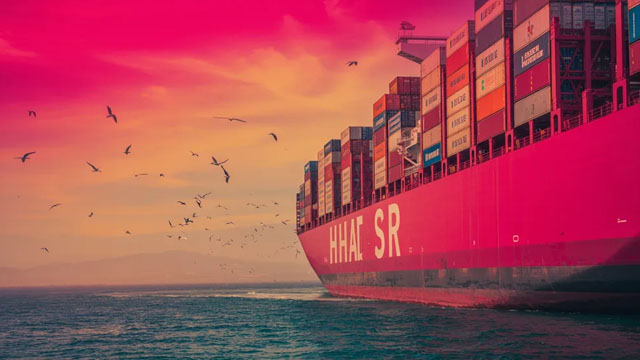
ZIM's pure-play spot market strategy creates a high-beta investment profile, generating explosive profits during freight rate surges (e.g., $1.1B net income in 2024Q3) but exposing the company to severe losses when rates normalize, as evidenced by the $86M loss in 2026Q1.
Price trend, volume and key moving averages
Trailing total returns as of 11/18/2026, which may include dividends or other distributions. Benchmark is S&P 500 (^GSPC).
Check whether operating performance supports the current valuation.
Recent results and news deserve attention only when they alter the forward view.
| Quarter | EPS (Act vs Est) | Revenue (Act vs Est) |
|---|---|---|
Q3 2026Latest Aug 19, 2026 | $0.53+2444.1% vs -$0.02 | $1.8B-0.3% vs $1.8B |
Q2 2026 May 20, 2026 | -$0.72-13.5% vs -$0.63 | $1.4B-5.9% vs $1.5B |
Q2 2026 Mar 9, 2026 | -$0.58+42.6% vs -$1.01 | $1.5B-5.2% vs $1.6B |
Q4 2025 Nov 20, 2025 | $1.02+33.2% vs $0.77 | $1.8B+2.3% vs $1.7B |
ZIM's Q3 earnings are likely to have benefited from stronger freight rates, Transpacific demand and capacity constraints, though elevated bunker costs remain a concern.
ZIM (ZIM) doesn't possess the right combination of the two key ingredients for a likely earnings beat in its upcoming report. Get prepared with the key expectations.
ZIM Integrated Shipping Services Ltd. is a Strong Buy with a $35 price target, reflecting both the Hapag-Lloyd buyout and robust H2 earnings. I estimate between $9 to $10 EPS for ZIM in H2 2026, as container rates remain unusually strong and realized rates significantly exceed Q2 levels. Merger approval risk remains, with Israeli national security concerns delaying the process. If blocked, shareholders will receive no compensation.
BOOM, DINO, CVE, ZIM and PKX stand out with attractive EV-to-EBITDA ratios and strong earnings outlook.
Benchmark ZIM against direct peers instead of judging its metrics in isolation.
Key metrics vs top competitors for ZIM Integrated Shipping Services Ltd. (ZIM)
| Company | Price | Market Cap | P/E Ratio | Rev Growth (1Y) | Net Margin | ROE | Div Yield |
|---|---|---|---|---|---|---|---|
| $29.69 | $3.58B | 25.85 | -18.07% | 2.15% | 3.52% | 14.41% | |
| $212.55 | $6.43B | 11.88 | -2.26% | 14.58% | 19.25% | 0.68% | |
| $27.16 | $3.03B | 10.55 | -17.62% | 23.87% | 11.71% | 1.1% | |
| $146.80 | $2.67B | 4.96 | 2.8% | 51.26% | 13.97% | 2.34% | |
| $12.95 | $1.56B | 4.67 | -57.87% | 40.5% | 14.82% | 5.09% | |
| $41.81 | $1.5B | 3.87 | 8.63% | 49.78% | 20.37% | 5.09% |
ZIM Integrated Shipping Services Ltd. (ZIM) vs competitors — business, growth, and fundamentals comparison against the closest industry rivals.
Get notified when ZIM posts new earnings or crosses analyst targets
Free. No account needed. Unsubscribe any time.
ZIM Integrated Shipping Services Ltd. (ZIM) stock FAQ — growth, dividends, profitability & financials explained
ZIM Integrated Shipping Services Ltd. (ZIM) reported $6.44B in revenue over the trailing twelve months. Revenue was $6.90B in fiscal year 2025. That is 87% more than the $3.68B of fiscal year 2013.
ZIM Integrated Shipping Services Ltd. (ZIM) revenue fell by 24.9% over the trailing twelve months, compared with the twelve months before.
Yes. ZIM Integrated Shipping Services Ltd. (ZIM) earned $138.6M in net income over the trailing twelve months (a 2.2% net margin).
Yes. ZIM Integrated Shipping Services Ltd. (ZIM) pays a dividend that yields 14.41% at the current price, a high yield.
ZIM Integrated Shipping Services Ltd. (ZIM) had a return on equity (ROE) of 3.5% over the trailing twelve months. That is below the market's typical 10-15%.
ZIM Integrated Shipping Services Ltd. (ZIM) generated $1.42B in free cash flow over the trailing twelve months.